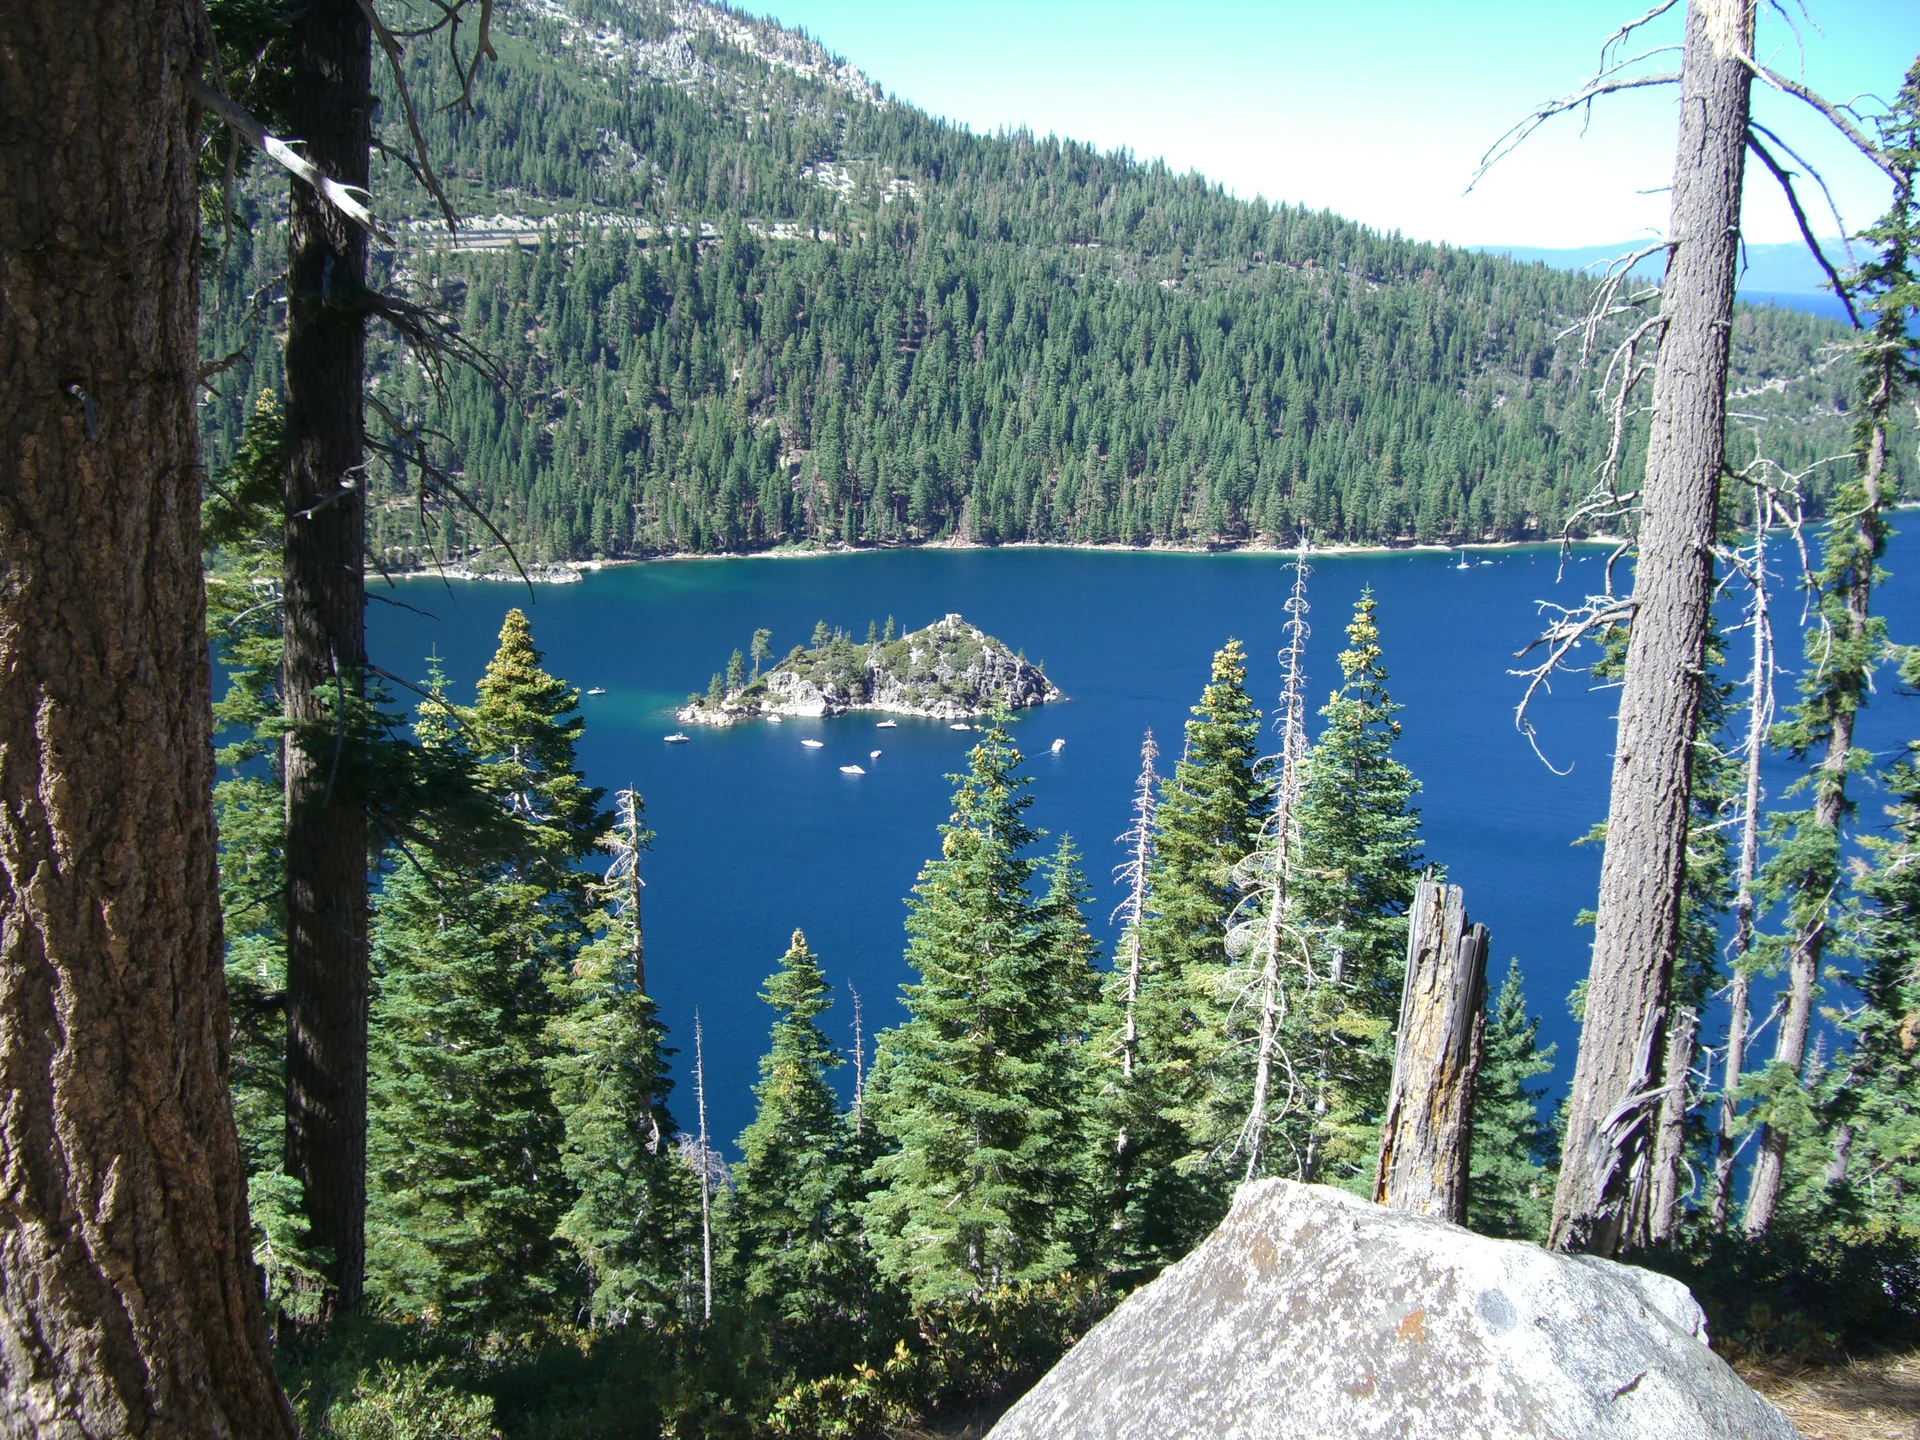
Pine-lined mornings. Blue water. A home you return to through the seasons. Whether Tahoe is your everyday address or your mountain retreat, begin with how you’ll live there, then build the financing around the actual property.
Find your stretch
of the California shore.
Tahoe City & the North Shore
Tahoe City, Carnelian Bay, Tahoe Vista and Kings Beach offer different starting points for a home search in Placer County. Visit the actual neighborhood, check winter access and compare the routes you’ll use for work, groceries and time outdoors.
Homewood & the West Shore
Explore Homewood and Tahoma with the parcel in hand. The West Shore crosses the Placer and El Dorado county boundary, so a familiar community name is not enough to identify the permitting authority or county. Ask about road maintenance, snow removal and property-specific costs.
South Lake Tahoe
The California city is in El Dorado County. City boundaries matter: the City of South Lake Tahoe administers its own vacation-home rental program, separately from the county’s program for unincorporated areas. Confirm the jurisdiction before building a rental plan.
Meyers & the South Shore surroundings
For a home in unincorporated El Dorado County, compare access, utilities and the property’s permitted use. A cabin, condominium and single-family home can require different reviews even when the asking prices look similar.
THE FINANCING CONVERSATION
Your everyday home.
Your mountain escape.
Start with the use.
Tell your loan officer whether the property will be your primary residence, a second home for personal use or an investment property. Occupancy affects eligibility and underwriting. A local rental permit and mortgage approval answer different questions.
Under Fannie Mae’s second-home requirements, the property must be a one-unit home suitable for year-round occupancy and used by the borrower for part of the year. Rental income cannot be used to qualify under that second-home classification. Ask your lender to review the full requirements and any rental or management agreement.
Fannie Mae: occupancy types and second-home requirements ↗
For a condo, bring association documents, insurance information, assessments and any rental restrictions into the conversation early. A resort-style listing or advertised rental history does not establish the property’s financing eligibility.
Plan beyond the principal and interest.
Request a property-specific insurance quote early, and include taxes, association dues, utilities, snow removal and ongoing maintenance in your budget. Ask about access in winter and the condition of the roof, heating and other systems during inspections.
Compare scenarios in the payment studio. If you are keeping your current home, include both homes’ expenses in the discussion. Avoid treating estimated vacation-rental income as guaranteed income or assuming a seller’s permit will transfer.
RESEARCH THE ACTUAL ADDRESS
Three places to check
before planning a rental.
Rules and permit availability can change. Check the authority for the specific parcel, plus any association restrictions, before relying on a rental strategy. These are the official California-side resources:
- Placer County: short-term rental program
- Unincorporated El Dorado County: vacation home rentals
- City of South Lake Tahoe: vacation home rentals
For a remodel, addition or vacant lot, investigate existing permits, land coverage and development rights before budgeting a project. The California Tahoe Conservancy’s land coverage and development rights guide explains where to start with local agencies and TRPA.
Sources checked October 31, 2026. Verify current parcel-specific requirements with the responsible agency.
California side only.
This guide covers California properties in Placer and El Dorado counties. Incline Village, Crystal Bay and Stateline are on the Nevada side and are outside this guide. Truckee is a separate nearby mountain market, not a California lakeshore community covered by these tables.
Does LMB have a Tahoe office?
Our home base is Danville. This guide helps you prepare a California home-financing conversation; it does not represent a separate Tahoe office. Program availability depends on the borrower, property and lender.